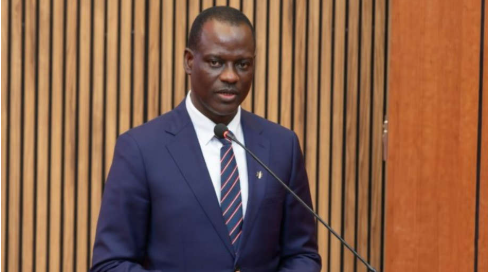
Nigeria’s Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has announced that the country is aiming for a seven per cent economic growth rate, surpassing IMF’s projections
The announcement was made during a press briefing at the Nigeria news conference held on the sidelines of the 2026 World Bank/IMF Annual Meetings in Bangkok, Thailand, on Saturday.
He described the IMF’s 4.3 per cent growth projection as conservative, expressing confidence that Nigeria’s economy could perform better as government accelerates reforms.
“The projections of the IMF have always turned out to be too conservative. This year will not be different,” he said.
The minister said that the government planned to accelerate growth through fiscal measures that would complement the Central Bank of Nigeria’s, CBN, monetary policy efforts.
He identified food, energy and logistics costs as major sources of inflationary pressure, adding that the government was addressing the challenges.
Oyedele said that lowering inflation to low single digits could create conditions for single-digit interest rates, reducing borrowing costs for businesses.
He said that businesses currently facing lending rates close to 30 per cent could achieve stronger growth if credit became more affordable.
Also Read: Oyedele warns new tax burden will kill the poor
The minister also attributed improvements in foreign exchange stability to efforts by the CBN, adding that the Naira had remained stable and was appreciating.
Oyedele said that the government’s broader reform agenda was designed to promote sustainable economic growth and deliver shared prosperity for Nigerians.
He described “Nigerian Rising” as the government’s way of communicating the country’s reform progress, growing international recognition and economic opportunities.
According to him, foreign exchange reforms and the rewriting of Nigeria’s tax system within two years are among the significant policy changes.
Oyedele urged Nigerians to look beyond negative headlines and recognise opportunities emerging from the country’s ongoing economic transformation.
On investors’ interests and public welfare, he said both were compatible, arguing that sustainable economic policies could benefit citizens and attract investment.
“Reversing key reforms, particularly fuel subsidy removal, can trigger capital flight, weaken the Naira and create further economic pressures
“Policy decisions must consider their long-term consequences. Reversing reforms can undermine investor confidence and economic stability,” he said.
Oyedele also clarified that discounts offered through commercial pricing arrangements should not automatically be described as fuel subsidies.
He said that Nigeria’s reform efforts were intended to strengthen the economy, attract investment and establish conditions for faster, sustainable growth.
NAN